COVID-19 Triggers Unique Market State in S&P 500
Dr. Manan Vyas's team found that correlations between S&P 500 stocks entered a previously unseen market state a few months into the COVID-19 pandemic, which persisted for over a year.


Researchers from the Instituto de Ciencias Físicas, Universidad Nacional Autónoma de México, and the Centro Internacional de Ciencias AC have identified a unique market state in the S&P 500 index correlated with the COVID-19 pandemic. The study, led by Dr. Manan Vyas and conducted with her team including Mijaíl Martínez-Ramos, Parisa Majari, and Professor Thomas Seligman, analyzed market behavior over a period of more than 15 years and discovered a novel state during the pandemic period. Their findings are published in the peer-reviewed journal PLOS ONE.
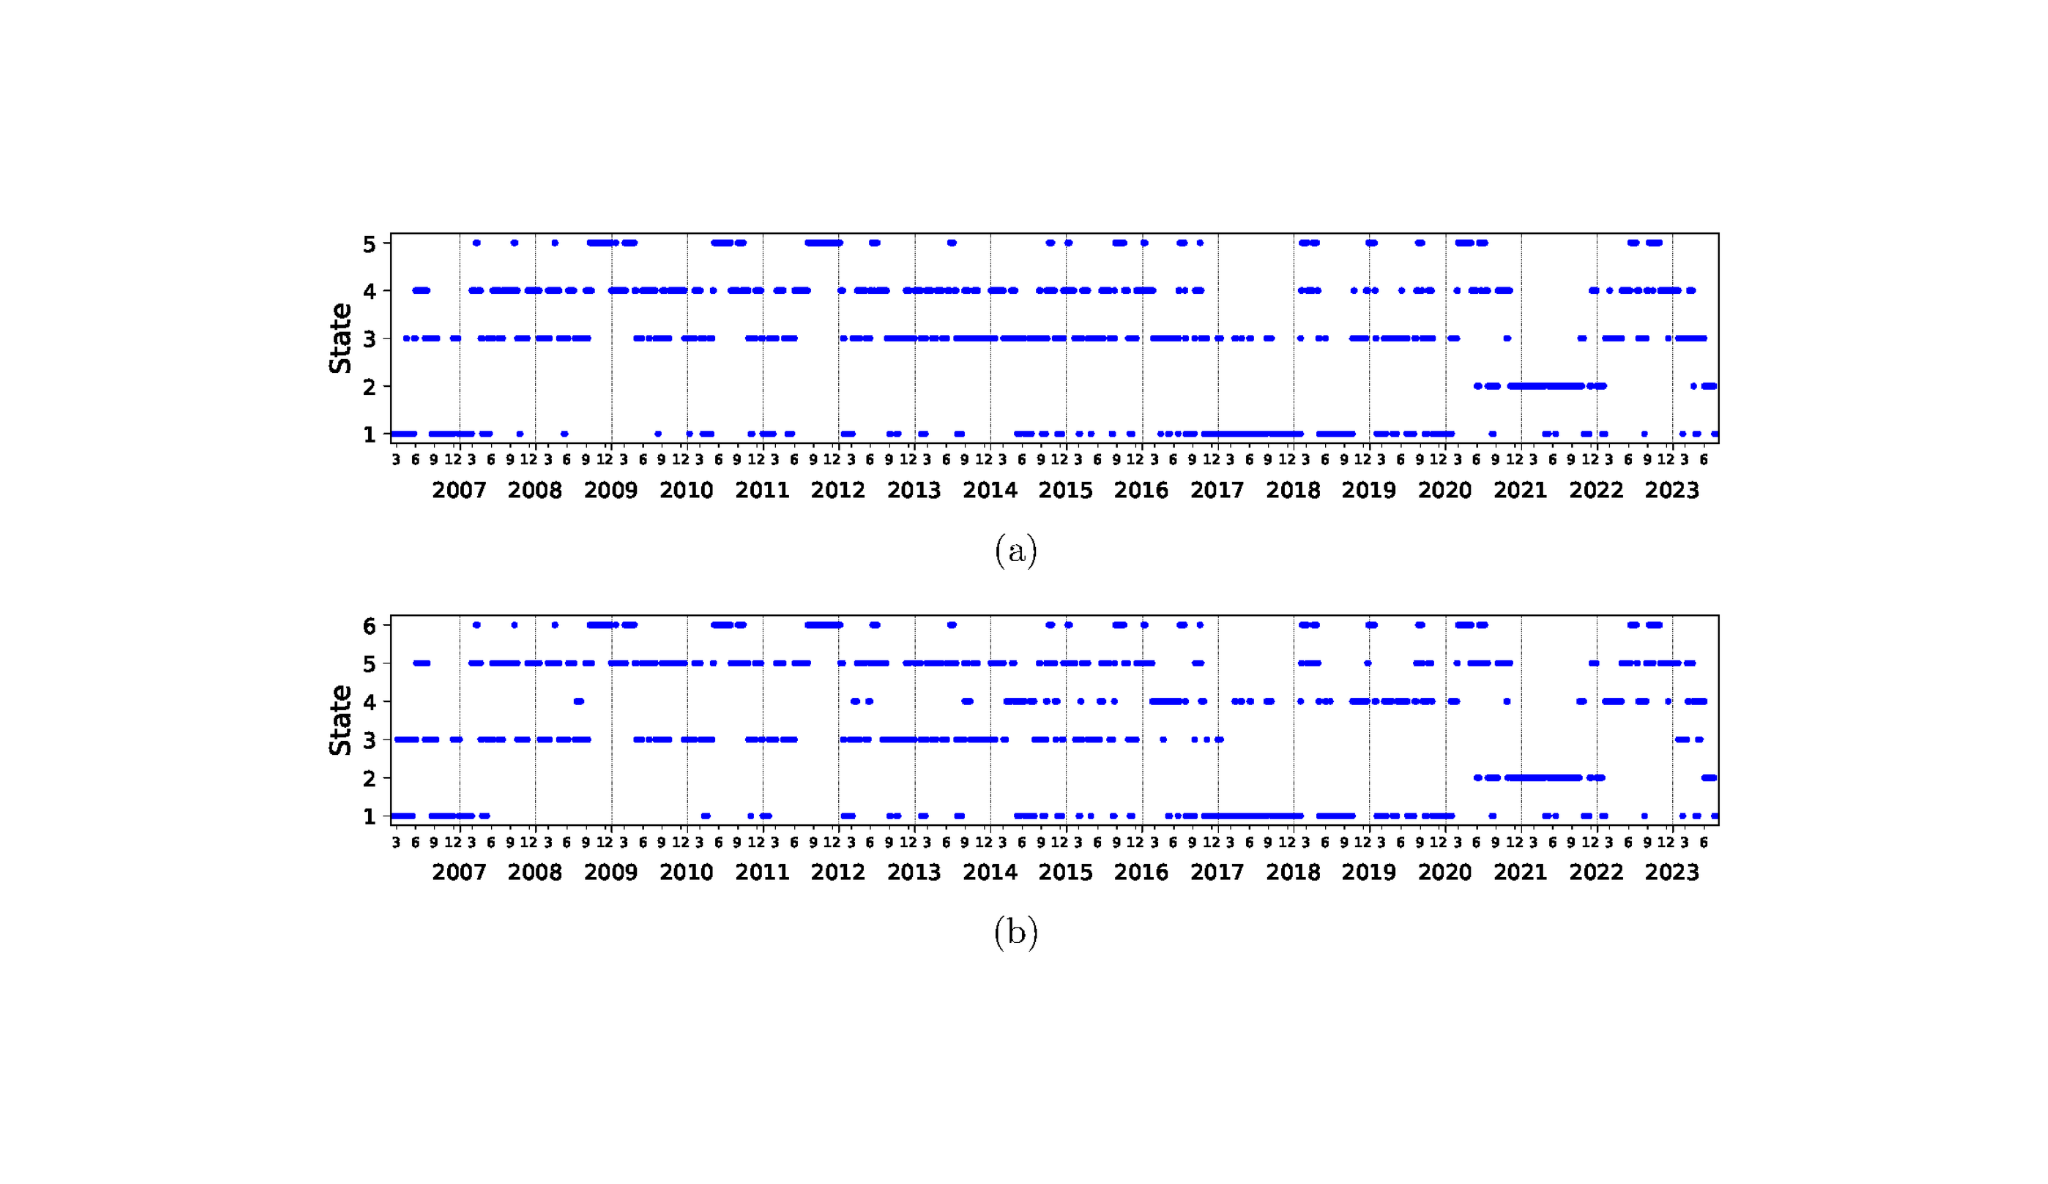
Analyzing the correlation of returns, the researchers observed a market state that was unprecedented in the historical data spanning over 15 years. This “COVID state” emerged following the initial financial panic of the pandemic and exhibited distinct characteristics not previously seen in the market. The study utilized the Pearson correlation matrix and relative correlations with respect to the S&P 500 index to identify this anomaly.
“The COVID state does not appear immediately after the pandemic’s onset but a few months later. This period corresponds to a crash well identified with panic sell-off,” said Dr. Vyas. This lag between the onset of the pandemic and the appearance of the COVID state is attributed to the initial market panic which masked the subtler correlations that emerged later.
The team’s analysis revealed that the COVID state was characterized by a low average correlation and a distinct clustering in the correlation matrix space. This state persisted for over a year, indicating a significant shift in market dynamics during the pandemic. The researchers employed k-means clustering to categorize the market states and confirmed the robustness of the COVID state across different numbers of clusters.
Dr. Vyas explained, “We found that a previously non-existent market state appears in a time frame closely related to the COVID pandemic. This suggests that the economic consequences and the mindset of the population during COVID had a profound impact on market behavior.”
Further analysis showed that the transition matrices during the COVID state were nearly tri-diagonal, reinforcing the uniqueness of this market condition. The equilibrium distributions indicated a distinct pattern of market behavior that was not observed in other periods.
The study’s findings have significant implications for understanding market dynamics during extreme events. The researchers emphasized the importance of considering relative correlations, which provided deeper insights into the market states by filtering out the dominant effects of the average correlation.
In conclusion, the appearance of the COVID state highlights the need for advanced analytical tools to detect and understand new market conditions. As Dr. Vyas noted, “This example will help us in our search for relevant parameters in the stock market beyond the highest eigenvalue of the Pearson correlation matrix.”
About the researchers

Manan Vyas
Manan Vyas completed her Bachelor of Science degree at Holkar Science College, Devi Ahilya Vishwavidyalaya, Indore, India, her Master's degree in Physics at Devi Ahilya Vishwavidyalaya, Indore, India and her doctoral degree in physics at Physical Research Laboratory, Ahmedabad, India.… She has done postdoctoral stays at Washington State University, Pullman, USA; Yeshiva University, New York, USA and at the Institute of Physical Sciences, National Autonomous University of Mexico, Cuernavaca, Mexico. She is level I of the SNI, PRIDE B and Member of the Mexican Physical Society. Since 2015, she has worked as a full-time researcher at the Institute of Physical Sciences of the UNAM where her research work is framed in the areas of random matrix theory, complex many-body systems, quantum chaos, econophysics and multivariate analysis. She has published more than 30 research articles in international peer-reviewed journals. She has been principal investigator for two PAPIIT projects and co-investigator for a CONAHCYT Fronteras project. She actively participates in teaching and human resources training. She has directed a bachelor's thesis and co-directed a master's thesis. She has three undergraduate students working with her and is co-supervisor of a doctoral thesis. She continually teaches basic and elective courses in faculty and postgraduate degrees in Physical Sciences at UNAM. She has been a member of several jury committees for undergraduate, master and doctoral students. She participates in editorial committees of international journals. Additionally, she participates in PAPIIT and CONAHCYT project evaluation committees. She has actively participated in the organization of several events (conferences, schools and workshops) at CIC A. C., Cuernavaca on topics related to her research. She received the EPL cash prize for best presentation at the Nuclei and Mesoscopic Physics conference held at Michigan State University, East Lansing, MI, USA in 2017. Currently, she is a co-editor for the special issue on ‘Entropy, Econophysics, and Complexity’ in the journal Entropy.

Dr. Parisa Majari
Dr. Parisa Majari recently completed her postdoctoral research at the Facultad de Química, Universidad Nacional Autónoma de México (UNAM), Mexico City. Dr. Majari's primary research interests lie in the transport behaviors and electronic properties of two-dimensional and quasi-two-dimensional materials.… She has investigated how factors such as time-dependent potentials and spin-orbit coupling affect transmission coefficients and dynamic properties, as well as the impacts of nanostructuring on electronic and optical properties for innovative applications. During her academic journey, Dr. Majari obtained her Bachelor's degree in Physics from Bu Ali Sina University and her Master's degree in Gravity from the same university. Her PhD research centered on the simulation of relativistic quantum mechanical effects in nano-optical structures and graphene, including the exploration of the properties of graphene electrons and the investigation of relativistic electrons in nonlinear harmonic oscillator potentials. Since completing her PhD, Dr. Majari has held several postdoctoral positions at the Instituto de Ciencias Físicas, UNAM, in Cuernavaca, Mexico. Her work has spanned diverse topics, from studying the Goos-Hänchen shifts in two-dimensional materials to advancing the analysis of financial markets using correlation matrices. Notably, during her postdoctoral research, she has also conducted advanced computational simulations using the Kwant software to investigate the electronic transport properties of few-layer graphene systems, shedding light on the band structure, density of states, and current-voltage characteristics of these 2D materials. Additionally, during her postdoctoral tenure, Dr. Majari was involved in a project that focused on designing and analyzing photonic waveguide arrays to simulate non-commutative spacetime dynamics, demonstrating their experimental potential. Dr. Majari is proficient in the use of various computational tools, including Maple, MATLAB, Python. She is also familiar with GAUSSIAN and Density Functional Theory (DFT). Dr. Majari is a candidate for the Sistema Nacional de Investigadores (SNI), Mexico's National System of Researchers.

Thomas H. Seligman
Thomas H. Seligman Born 1944, stateless, in Basel Switzerland in 1944, later Swiss and finally Mexican citizenship. Undergraduate studies: theoretical physics at the University of Basel. Ph.D. University of Tübingen and Posdocs in Mexico, Tübingen and Cologne.… Returning to Mexico in 1976 as a researcher at Universidad Nacional Autónoma de México first un Mexico City and later in Cuernavaca, were he still is active at age 80 to this day. Marcos Moshinsky and Hans Weidenmüller, where forming personality in his career; A course the former taught at ICTP was decisive for his move to Mexico. His research started with applications of Group Theory to Nuclear Physics and expanded to include Random Matrix Theory, Scattering Theory, Molecular Physics, and most recently Econophysics. An excursion into Seismology after the devastation 1985 earthquake in Mexico City led to an influential article in the Journal Nature. International collaborations Included the US, Canada, Brasil and most recently India. The most important prizes were The National for Science Prize of Mexico and te Alexander v. Humboldt Prize from Germany. He was Director and is actually President of the International Center for Sciences and was the founding President of the Academy of Science of Morelos. More than 200 papers in prestigious international Journals with more than 7000 citations as well as more than 50 thesis of levels between undergraduate and master and doctoral levels directed or codirected, mainly in Mexico, but also in Switzerland, Russia and Germany highlight his educational activities.
Journal reference
Martínez-Ramos, M. M., Vyas, M., Majari, P., & Seligman, T. H. “COVID anomaly in the correlation analysis of S&P 500 market states.” PLOS ONE (2024): 19(4): e0301238. https://doi.org/10.1371/journal.pone.0301238